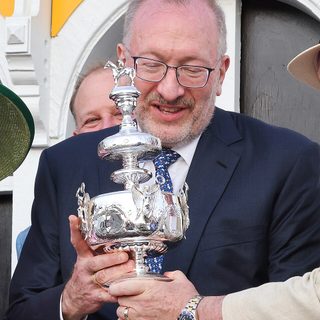
Co-founder and chief investor of the Baupost Group and author of "Margin of Safety" — often called the "Oracle of Boston".
Life story
Seth Klarman was born in 1957 in New York City to a Jewish family. His father, Herbert Klarman, was a public health economist at Johns Hopkins University, and his mother was a psychiatric social worker. After the family moved to Baltimore, his parents divorced when he was six.
He was drawn to commerce early: at four he turned his room into a "store" with price tags, at ten he bought a single share of Johnson & Johnson because he knew its Band-Aids, and by twelve he was regularly calling brokers for quotes. He also ran small ventures such as paper routes, a snow-cone stand and selling stamps and coins.
He graduated magna cum laude in economics from Cornell University in 1979 and later earned an MBA from Harvard Business School, where he was a Baker Scholar.
How they got started
As a student he interned at the Mutual Shares fund, where he met the well-known value investors Max Heine and Michael Price. After college he worked there for about 18 months before going to business school.
In 1982 Harvard professor William Poorvu and his partners (Howard Stevenson, Jordan Baruch and Isaac Auerbach) set up a firm to manage their family money and recruited the young Klarman. The fund started with $27 million and Klarman's initial salary was $35,000 a year. The name "Baupost" is an acronym built from the founders' surnames.
In 1991 he published his only book, "Margin of Safety"; because few copies were printed, used copies now sell for thousands of dollars. In 2008 he edited the 6th edition of Graham and Dodd's classic "Security Analysis". Baupost's assets grew to around $30 billion in the 2010s.
Investment style
Klarman is a value investor in the Benjamin Graham tradition: he looks for neglected, underpriced assets that can be bought with a margin of safety. Avoiding permanent loss comes first; returns come second.
A Baupost hallmark is holding a large share of the portfolio in cash (at times 30–50%) when bargains are scarce. Beyond ordinary stocks, the firm invests in distressed debt, real estate and other unconventional assets, so its 13F filing shows only part of what it does.
Best decisions
Buying debt cheaply in the 2008 crisis
During the financial crisis Baupost raised $4 billion of new capital and bought distressed bonds, including CIT Group debt at about 65 cents on the dollar. Those bond positions later appreciated by roughly 25%.
Facet Biotech (2009)
Baupost bought Facet Biotech at $9 a share when the company held about $17 a share in net cash. Abbott later acquired it for $27 a share. Deals like this helped the fund finish 2009 up about 27%.
Long-term record
According to Wikipedia, Baupost has averaged roughly 20% a year since inception and ranks among the funds with the largest cumulative net gains in Bloomberg's rankings.
Biggest mistakes
Losses in 2008
As security prices collapsed at the height of the crisis, Baupost's funds lost roughly 7–13% in 2008 — Klarman's caution did not fully shield it from the market shock.
A weak decade (2014–2024)
According to Wikipedia, Baupost returned only about 4% a year from 2014 to 2024, far behind the US stock market. Large cash holdings and a cautious style left it lagging during a long bull market.
Today
As of 2026 Klarman is 69 and remains president and chief investor of Baupost. The firm's assets were estimated at about $25 billion in 2022. Forbes put his personal fortune at $1.3 billion in January 2025.
He keeps a very low public profile and rarely gives interviews. In July 2025 he was named chair of the board of the Broad Institute, and he is a co-owner of the racing stable Klaravich Stables.
What to learn from following the portfolio
- Baupost's 13F shows only US equities — the large share of the fund in debt, real estate and cash is invisible here, so the list on the Portfolio tab is not his full view.
- The most interesting signal is a new position or a sharply increased stake: Klarman tends to buy unloved companies others are fleeing, so such a purchase often reflects deep work.
- 13F data arrives up to 45 days after quarter-end; Klarman's purchase price and today's price can differ widely — blind copying is not a strategy.
- Islamic-finance lens: Baupost at times holds financials, insurers and heavily indebted or restructuring companies, which usually fail halal screening; technology, healthcare and consumer names may pass. Check each position's halal status on the Portfolio tab.
An introduction based on public sources — not investment advice. Spotted an error? Let us know.